Purchasing a medical alert system is a straightforward investment in personal safety, but navigating the payment options requires precise information. Many seniors and caregivers naturally assume that federal healthcare programs will foot the bill for these vital personal emergency response systems, often referred to as PERS. The reality, however, is far more fragmented and depends heavily on a patchwork of private policies, state regulations, and veteran status.
For families researching how to pay for medical alert systems, understanding coverage options can mean the difference between seamless safety and unexpected out-of-pocket expenses. Coverage is rarely a one-size-fits-all proposition and depends entirely on an individual’s specific insurance plan, state of residence, and history of military service.
To help families make informed decisions, a breakdown of how various government and private entities handle personal emergency response systems reveals distinct pathways and limitations.
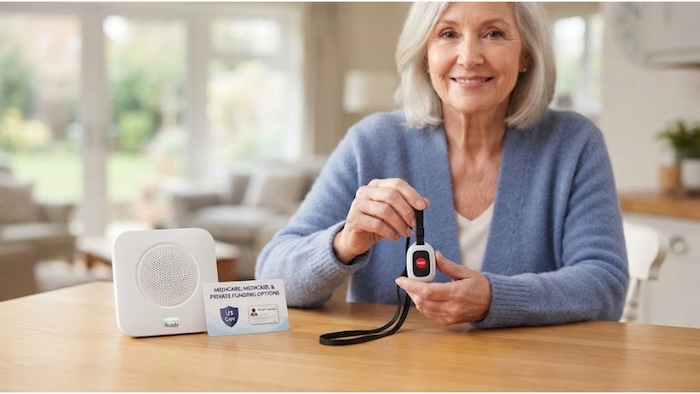
Does Medicare Cover Medical Alert Systems?
For millions of older adults relying on Original Medicare, Parts A and B, the answer regarding coverage is a definitive no. The Centers for Medicare & Medicaid Services do not classify medical alert systems as durable medical equipment, or DME. Because these emergency pendants and base stations are not deemed medically necessary under strict Original Medicare guidelines, beneficiaries who rely solely on this type of coverage will find themselves paying one hundred percent of the cost out of pocket.
However, the landscape shifts when examining Medicare Advantage, or Part C, plans. Because these plans are administered by private insurance companies rather than the federal government, they possess the flexibility to offer supplemental health benefits that go beyond Original Medicare. Some Medicare Advantage plans choose to cover partial or full costs for medical alert systems, largely because keeping seniors safe at home helps prevent costly hospital readmissions and emergency room visits. To determine eligibility, policyholders must thoroughly review their specific Summary of Benefits document or contact their insurance provider directly to confirm whether a chosen device qualifies for supplemental coverage.
Medicaid and Home and Community-Based Services Waivers
Medicaid offers a more robust framework for coverage, though it remains highly conditional and subject to local policy. Under Medicaid’s Home and Community-Based Services waivers, commonly known as HCBS waivers, many states cover the cost of medical alert systems. These programs are specifically designed to help seniors age safely in place within their communities rather than forcing an early transition into a nursing facility or institutional care setting.
Because Medicaid is administered at the state level rather than federally, coverage rules vary dramatically from one state to the next. Families must apply for the specific waiver program operating within their state of residence. If an application is approved, Medicaid typically steps in to pay the monthly monitoring fee directly to the vendor. At the same time, these state programs may restrict which equipment brands and hardware options beneficiaries are allowed to choose.
VA Benefits for Medical Alert Systems
For eligible military veterans, the path to obtaining full coverage is often the most direct and reliable. The Department of Veterans Affairs provides medical alert systems to qualifying veterans at absolutely no cost. Rather than purchasing a system independently and seeking reimbursement later, veterans must request a formal consultation with their primary care provider within the VA health system.
If the primary care provider determines that a medical alert system is clinically necessary for the veteran’s safety, the VA orders the equipment directly from an approved vendor. Under this arrangement, the VA covers both the initial hardware and the ongoing monthly monitoring fees, ensuring continuous protection without financial strain.
Alternative Avenues and Financial Planning
When government assistance programs and insurance policies fall short, families frequently turn to alternative avenues to help lower their out-of-pocket expenses. Flexible Spending Accounts and Health Savings Accounts can sometimes be utilized depending on individual plan rules and medical necessity documentation. Additionally, local community resources, charitable grants, and Area Agencies on Aging often provide guidance or financial assistance programs for seniors striving to maintain their independence at home.
Caregiving is an inherently exhausting role, and the added frustration of fighting with insurance bureaucracies can compound an already heavy burden. Original Medicare largely leaves caregivers on their own in this arena, forcing families to navigate a complex maze of private Advantage plans, conditional Medicaid waivers, and VA requirements. Experts strongly recommend that older adults and their families investigate these coverage options well in advance, rather than waiting for a sudden health crisis or a dangerous fall to force the issue.
Reaching out to health insurance providers ahead of time to ask whether modern medical alert systems are covered under a specific Part C policy or Medicaid waiver can save families considerable stress and financial hardship. Even if an insurance company ultimately denies coverage, exploring alternative funding methods or choosing to pay out of pocket is often a necessary step for aging safely at home. For many households, the monthly cost of a medical alert system remains a minor expense compared to the devastating physical, emotional, and financial toll of an undetected emergency.