Purchasing a medical alert system is widely recognized as a straightforward investment in personal safety, yet navigating the maze of payment options requires precise information that many families lack. For many seniors and family caregivers embarking on the search for personal emergency response systems, a common assumption is that federal healthcare programs will automatically foot the bill. However, the financial reality surrounding these life-saving devices proves to be far more fragmented, leaving many to discover that coverage depends entirely on an individual’s specific insurance plan, state of residence, and veteran status.
Understanding how government entities and private insurance companies handle personal emergency response systems, commonly known as PERS, has become increasingly vital as more aging adults seek to maintain their independence at home. While modern medical alert devices offer advanced features like automatic fall detection and GPS tracking, the financial burden of acquiring them often falls squarely on the shoulders of seniors and their loved ones unless they fall into specific coverage categories.
Medicare Coverage Realities
For millions of older adults enrolled in Original Medicare, covering Parts A and B, the answer regarding financial assistance for medical alert systems is a definitive negative. The Centers for Medicare & Medicaid Services do not classify personal emergency response systems as durable medical equipment. Because federal guidelines do not deem these devices to be medically necessary under Original Medicare parameters, beneficiaries must pay the full cost entirely out of pocket if this serves as their sole form of health insurance coverage.
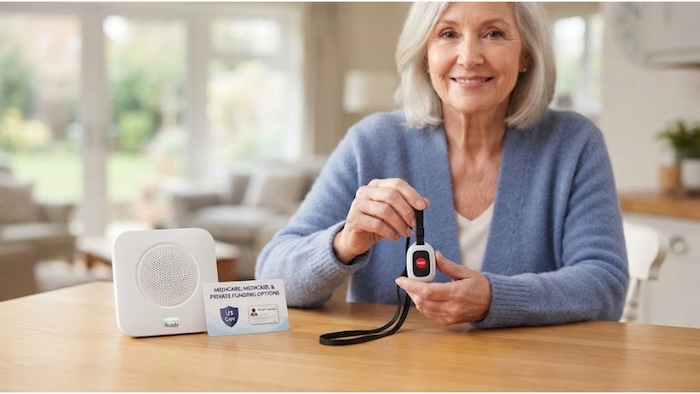
The financial landscape shifts somewhat for those enrolled in Medicare Advantage, or Part C, programs. Because private insurance companies administer these alternative plans, they possess the administrative flexibility to offer supplemental health benefits that traditional Medicare excludes. A number of Medicare Advantage plans cover partial or full costs for medical alert systems, viewing the technology as a proactive measure to prevent costly hospital readmissions following a fall or medical emergency. Beneficiaries must carefully examine their specific Summary of Benefits document or contact their insurance provider directly to confirm whether a chosen device qualifies for these supplemental perks.
Medicaid Waivers and State-Level Support
Medicaid offers a more robust path toward coverage, though it remains highly conditional and subject to complex bureaucratic rules. Under Medicaid’s Home and Community-Based Services waivers, many individual states cover the cost of medical alert systems as part of broader initiatives to help seniors age in place safely rather than forcing an early transition into a nursing facility.
Because Medicaid is administered at the state level rather than uniformly across the nation, coverage rules vary dramatically depending on where a policyholder resides. Seniors and caregivers must apply specifically for the designated waiver program operating within their home state. When approved under these waiver programs, Medicaid typically coordinates directly with the vendor to pay the ongoing monthly monitoring fee. Even so, these programs frequently restrict beneficiaries to a pre-approved list of equipment brands and service providers, limiting consumer choice in exchange for financial relief.
Department of Veterans Affairs Benefits
Among all government programs, the Department of Veterans Affairs provides the most straightforward and reliable path to full coverage for those who have served in the military. The VA supplies medical alert systems to eligible veterans at absolutely no cost, removing the traditional hurdle of purchasing equipment upfront and seeking a cumbersome reimbursement later.
To access this benefit, a veteran must request a formal consultation with their assigned VA primary care provider. If the clinician determines that a medical alert system is clinically necessary to ensure the veteran’s safety at home, the department orders the equipment directly from an approved federal vendor. Furthermore, the VA covers both the initial hardware and all ongoing monthly monitoring fees, ensuring continuous protection without financial strain for qualifying individuals.
Alternative Funding Avenues
When government assistance programs fall short or fail to apply, families frequently turn to alternative financial avenues to help lower their out-of-pocket expenses. Flexible Spending Accounts and Health Savings Accounts can sometimes be utilized to purchase medical alert systems, provided the consumer obtains a formal letter of medical necessity from a licensed physician.
Additionally, local resources such as Area Agencies on Aging often provide guidance, grants, or localized financial programs designed to assist older adults with safety modifications and assistive technology. When all other funding sources are exhausted, many families ultimately decide to pay out of pocket, weighing the monthly subscription expense against the catastrophic physical and financial toll of an undetected medical emergency.
As caregiving responsibilities continue to place immense emotional and physical demands on families, navigating insurance policies for safety technology can quickly become an exhausting endeavor. Industry experts emphasize the importance of researching coverage options well before a medical crisis occurs. By contacting health insurance providers in advance to inquire about modern medical alert system policies under specific Part C plans or Medicaid waivers, seniors and their caregivers can establish a reliable safety net and secure peace of mind for the journey of aging in place.