Managing an older adult’s prescription medications has long been a persistent financial drain for families and caregivers alike. Historically, individuals were forced to navigate convoluted coverage phases that made long-term budgeting nearly impossible. However, the sweeping Medicare Part D changes for the 2026 plan year eliminate much of that historical volatility, introducing forced financial predictability into the modern prescription drug market.
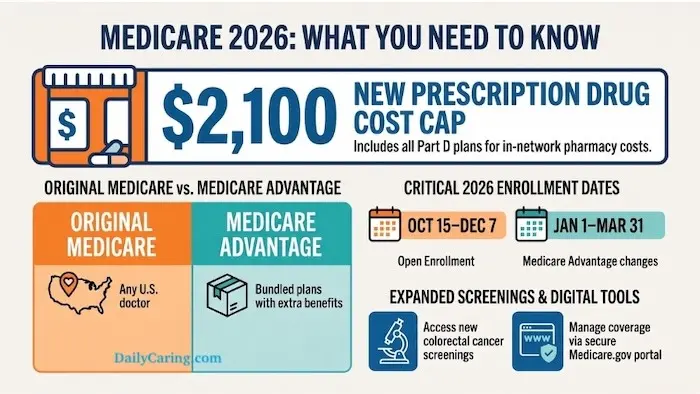
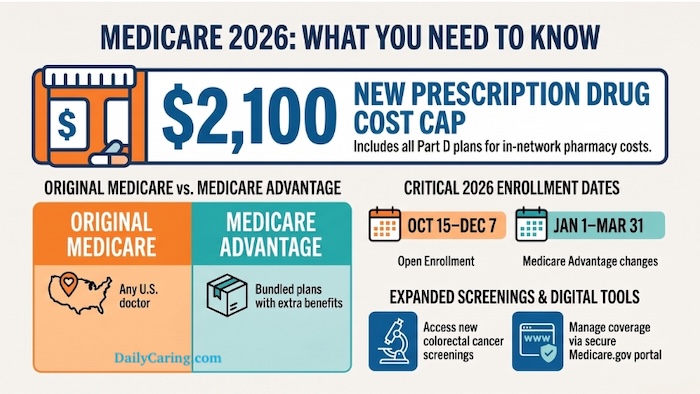
Thanks to the final implementation phases of the landmark Inflation Reduction Act, out-of-pocket costs for covered prescription drugs are now strictly capped at $2,100 annually for beneficiaries. Alongside this hard ceiling, the maximum standard deductible for the plan year has been legally established at $615. These structural adjustments represent a massive shift in how eldercare financial planning must be approached, offering much-needed relief to millions of seniors and their caregivers who previously faced unpredictable medical expenses.
For over a decade, perhaps the most destructive and anxiety-inducing element of Medicare Part D for seniors was the coverage gap, widely recognized by the public as the "donut hole." During this frustrating phase, seniors who reached a specific cumulative spending threshold suddenly found themselves responsible for an enormous percentage of their total drug costs. They were forced to shoulder these exorbitant expenses until their spending finally pushed them into catastrophic coverage.
As of the 2026 plan year, the donut hole is permanently dead. It no longer exists within the framework of Medicare Part D.
Understanding these modern Part D policy updates and associated prescription caps has consequently become a mandatory component of comprehensive eldercare financial planning. Under the current rules, once an enrollee spends exactly $2,100 out of pocket in a single calendar year, their specific Part D plan or Medicare Advantage plan steps in to pay 100% of the cost of covered medications for the remainder of that year. There are no unexpected exceptions, and the old catastrophic phase—where patients were previously required to pay a lingering 5% coinsurance—has been entirely abolished. Once the threshold is met, the patient’s out-of-pocket cost for covered drugs drops straight to zero.
Despite the clear financial protections offered by the new spending caps, healthcare advocates warn that beneficiaries should not assume their current insurance coverage is entirely safe. Insurance companies are businesses that are not absorbing these new multi-billion-dollar cost obligations out of the goodness of their hearts. In response to the federal mandates, insurers have begun aggressively manipulating their covered drug lists, commonly known as formularies, and shifting essential medications into higher pricing tiers in an effort to offset the mandated caps.
A prescription medication that was fully covered and affordable in 2025 may be dropped entirely or restricted by a prior authorization requirement in 2026. Because of this risk, families must meticulously verify that their aging loved one’s specific medications remain securely on their chosen plan’s formulary during the Annual Enrollment Period. This step is critical because if a drug is ultimately excluded from the formulary, any money spent out of pocket to purchase it will not count toward the vital $2,100 annual spending cap.
To prevent seniors from facing immediate, burdensome deductible hits during the cold winter month of January, the 2026 regulations mandate the continuation of the Medicare Prescription Payment Plan. This opt-in program was designed specifically to allow enrollees to smooth their out-of-pocket prescription costs evenly over the course of the entire calendar year rather than absorbing them all at once.
Instead of being forced to pay a large, intimidating lump sum at the pharmacy counter right at the start of the year, a caregiver can officially opt their loved one into this structured payment arrangement. Under this workflow, the pharmacy bills the insurance plan as usual, and the insurance plan subsequently sends the enrollee a manageable monthly bill to spread out the financial impact. Participation in this program is entirely voluntary, meaning beneficiaries who prefer to pay standard deductibles and copays at the point of sale may continue to do so until they ultimately hit the $2,100 ceiling.
Another critical, though frequently underreported, aspect of the recent Medicare Part D restructuring is the premium stabilization program. In order to prevent insurance providers from simply jacking up monthly premiums to compensate for the new out-of-pocket spending caps, the law explicitly caps base premium increases at a maximum of 6% per year.
However, industry experts emphasize that this federal stabilization safeguard only applies strictly to the base premium calculations. Individual plan premiums will continue to fluctuate based on market factors and regional offerings, making annual comparison shopping an absolute necessity for anyone wanting to keep their overall healthcare overhead as low as possible. Reviewing available coverage options early in the enrollment cycle gives families a distinct financial advantage.
The complete elimination of the coverage gap means that beneficiaries now move seamlessly from their initial coverage phase directly into total coverage once they hit the $2,100 out-of-pocket threshold. For caregivers balancing complex household budgets, this predictability provides a foundation for more stable long-term care planning. Yet, the ongoing shifts in insurance company formularies mean that constant vigilance remains required.
As families evaluate their options under the updated regulations, consulting official federal resources and keeping a close eye on plan documents remains essential. The landscape of senior healthcare financing has shifted fundamentally, and while the new framework offers unprecedented protections against catastrophic drug costs, navigating the fine print of plan formularies and premium structures will continue to dictate the true financial reality for millions of older adults across the country.