Purchasing a medical alert system is widely recognized as a straightforward investment in personal safety and aging in place, but navigating the myriad payment options requires precise and up-to-date information. Many seniors and family caregivers frequently assume that federal healthcare programs will automatically foot the bill for these personal emergency response systems, commonly known as PERS. However, the financial reality remains far more fragmented and complex than many anticipate.
For families researching how to fund these vital safety devices, coverage depends entirely on a series of variable factors, including a specific insurance plan, state of residence, and veteran status. Understanding the landscape of government and private coverage is essential for avoiding unexpected out-of-pocket expenses during a time when safety and financial clarity are paramount.
The foundational issue for many beneficiaries begins with Original Medicare. Under current guidelines established by the Centers for Medicare & Medicaid Services, Original Medicare, which includes Parts A and B, does not provide coverage for medical alert systems. Federal regulators do not classify personal emergency response systems as durable medical equipment, meaning they are not deemed medically necessary under standard Original Medicare guidelines. Consequently, policyholders relying solely on Original Medicare will find themselves paying one hundred percent of the equipment and monitoring costs out of pocket.
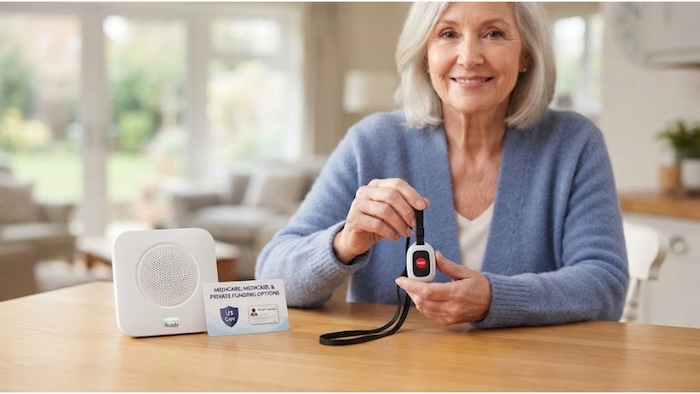
The financial equation shifts considerably when examining Medicare Advantage plans, often referred to as Part C. Because private insurance companies administer these alternative plans, they possess the regulatory flexibility to offer supplemental health benefits that extend beyond standard federal coverage. A growing number of Medicare Advantage plans now cover partial or even full costs for medical alert systems, viewing the technology as a proactive measure to prevent costly hospital readmissions resulting from unassisted falls. Because benefits vary widely from one private insurer to another, policyholders must thoroughly review their specific annual Summary of Benefits documents or contact their insurance providers directly to confirm whether a chosen device qualifies for reimbursement or inclusion.
Beyond Medicare, Medicaid offers a more robust yet highly conditional pathway for coverage. Through Medicaid’s Home and Community-Based Services waivers, commonly known as HCBS waivers, numerous states cover the cost of personal emergency response systems. These waiver programs are explicitly designed to help older adults age safely in the comfort of their own homes rather than transitioning prematurely into costly institutional settings like nursing facilities.
Because Medicaid is administered at the individual state level, coverage rules and product allowances vary dramatically across geographic lines. Families must apply for the specific waiver program authorized in their home state. If an application is approved, Medicaid typically steps in to pay the monthly monitoring fee directly to the vendor. However, this administrative arrangement often comes with restrictions, meaning beneficiaries may be required to choose from a limited list of pre-approved equipment brands and hardware providers rather than selecting any device on the open market.
For military veterans, the path toward securing a medical alert system is considerably more streamlined and offers the clearest route to comprehensive coverage. The Department of Veterans Affairs provides personal emergency response systems to eligible veterans at absolutely no cost. Unlike commercial programs where consumers purchase a device and seek reimbursement, the VA process requires the veteran to request a formal consult with their primary care provider within the VA healthcare system.
If the primary care provider determines that a medical alert system is medically necessary to ensure the veteran’s safety at home, the department orders the equipment directly from an approved vendor. Under this arrangement, the VA covers both the initial hardware and the ongoing monthly monitoring fees, eliminating financial barriers for qualifying individuals who served the nation.
For individuals who do not qualify for government-backed assistance through Medicaid or the VA, alternative avenues exist to help lower out-of-pocket expenses. Many families utilize flexible spending accounts or health savings accounts to pay for medical alert hardware and services on a pre-tax basis. Additionally, local community resources, such as regional Area Agencies on Aging, frequently direct caregivers toward grants, localized subsidies, or charitable programs designed to assist seniors with safety technology purchases.
The burden of caregiving is inherently exhausting, and navigating a labyrinth of insurance policies, conditional waivers, and bureaucratic hurdles often exacerbates an already stressful situation. Experts advise that families should not wait for a catastrophic medical emergency or a severe fall to figure out their coverage options. Proactive communication with health insurance providers well in advance can clarify whether modern medical alert systems are integrated into a specific Part C policy or state Medicaid waiver.
When insurance companies deny coverage, turning to alternative funding methods such as flexible spending accounts, contacting local aging agencies, or absorbing the cost out of pocket remains a necessary reality for many households. For a vast number of older adults, a medical alert system serves as an absolute requirement for aging safely at home, where the modest monthly monitoring fee pales in comparison to the devastating physical, emotional, and financial toll of an undetected medical crisis.
Industry analysts and advocates continually stress that while financial policies vary significantly by jurisdiction, individual plans, and calendar years, early research remains the best defense against unexpected healthcare costs. Caregivers and seniors are encouraged to consult with licensed insurance professionals, financial planners, or elder law attorneys to verify specific coverage criteria before committing to long-term service contracts.