Purchasing a medical alert system is widely regarded as a straightforward investment in personal safety and aging in place, but navigating the complex web of payment options requires precise information. Many seniors and their family caregivers frequently assume that federal healthcare programs will automatically foot the bill for these personal emergency response systems. However, the financial reality remains far more fragmented across different insurance networks, government bodies, and private options.
For families researching how to pay for medical alert systems, coverage depends entirely on specific insurance plans, individual state of residence, and veteran status. Understanding what government programs and private entities will cover regarding personal emergency response systems is critical for preventing unexpected out-of-pocket expenses during a medical emergency.
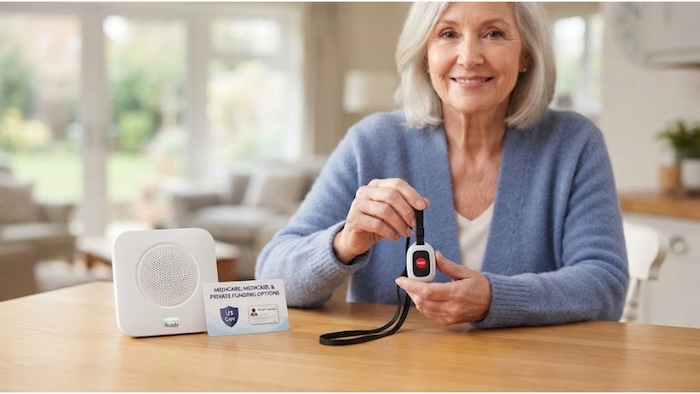
When evaluating government-backed healthcare, the distinction between various plans becomes crucial. Original Medicare, which encompasses both Part A and Part B, does not offer coverage for medical alert systems. The Centers for Medicare and Medicaid Services explicitly do not classify personal emergency response systems as durable medical equipment. Because they are not deemed medically necessary under the strict guidelines of Original Medicare, policyholders must pay one hundred percent of the equipment and monitoring costs out of pocket if this serves as their sole form of health insurance coverage.
Conversely, Medicare Advantage, or Part C, alters the financial equation for many older adults. Because these plans are administered by private insurance companies rather than the federal government, they possess the flexibility to offer supplemental health benefits designed to support aging in place. Many Medicare Advantage plans now cover partial or full costs for medical alert systems as a preventive measure to reduce costly hospital readmissions resulting from unassisted falls. Beneficiaries must carefully review their specific plan documents or contact their providers directly to confirm whether a chosen device qualifies under their policy’s supplemental benefits.
Medicaid presents a more robust financial option, though eligibility remains highly conditional and varies significantly by region. Under Medicaid’s Home and Community-Based Services waivers, numerous states absorb the cost of medical alert systems to help seniors remain safely in their homes rather than transitioning prematurely to costly institutional nursing facilities. Because Medicaid programs are administered at the state level rather than federally, coverage rules and approved equipment brands differ widely across state lines. Beneficiaries must apply for specific waiver programs within their jurisdiction. When approved, state Medicaid offices typically disburse the monthly monitoring fees directly to the authorized vendor.
For military veterans, the Department of Veterans Affairs provides the most direct and reliable path to full coverage. The VA supplies medical alert systems to eligible veterans at no personal cost, eliminating the need to purchase equipment independently and seek reimbursement. Instead, veterans must request a formal medical consult with their assigned VA primary care provider. If the clinician determines that a personal emergency response system is clinically necessary for the veteran’s safety at home, the department orders the technology directly through an approved commercial vendor, covering both the hardware and the ongoing monthly monitoring fees.
Families who do not qualify for government assistance programs still have alternative avenues available to help lower their overall out-of-pocket expenses. Private financial tools such as flexible spending accounts and health savings accounts can often be utilized to pay for eligible medical devices, depending on current tax regulations and plan rules. Additionally, local community organizations, charitable grants, and regional aging resources frequently provide financial assistance or subsidies for seniors who cannot otherwise afford the monthly subscription fees associated with personal emergency response monitoring.
The financial burden of caregiving is already substantial, and untangling insurance policies can add considerable stress to families supporting aging relatives. While Original Medicare leaves a significant gap in coverage, forcing caregivers to navigate a maze of private Advantage plans, conditional Medicaid waivers, and VA protocols, proactive planning remains essential. Experts advise families to investigate their insurance coverage well before a medical emergency occurs by contacting plan administrators to ask whether modern medical alert systems are included under specific policies.
When insurance providers deny coverage, alternative funding sources—such as flexible spending accounts, local community agencies, or direct out-of-pocket payments—frequently become necessary. For countless older adults, a reliable medical alert system is a fundamental requirement for maintaining independence and aging safely at home, with monthly subscription fees representing a minor fraction of the physical and financial toll associated with an undetected accident.